On October 22, 2026, an executive order titled “Decreasing Housing Costs for the American People” was signed. It covers several areas of housing finance, and I will walk through them one at a time over the coming days. Today I am focusing on one piece: the reforms to mortgage insurance and title insurance.
What does the executive order say about mortgage insurance?
The order directs the Federal Housing Finance Agency (FHFA) to create a pilot program for Fannie Mae and Freddie Mac designed to lower mortgage insurance costs for homeowners.
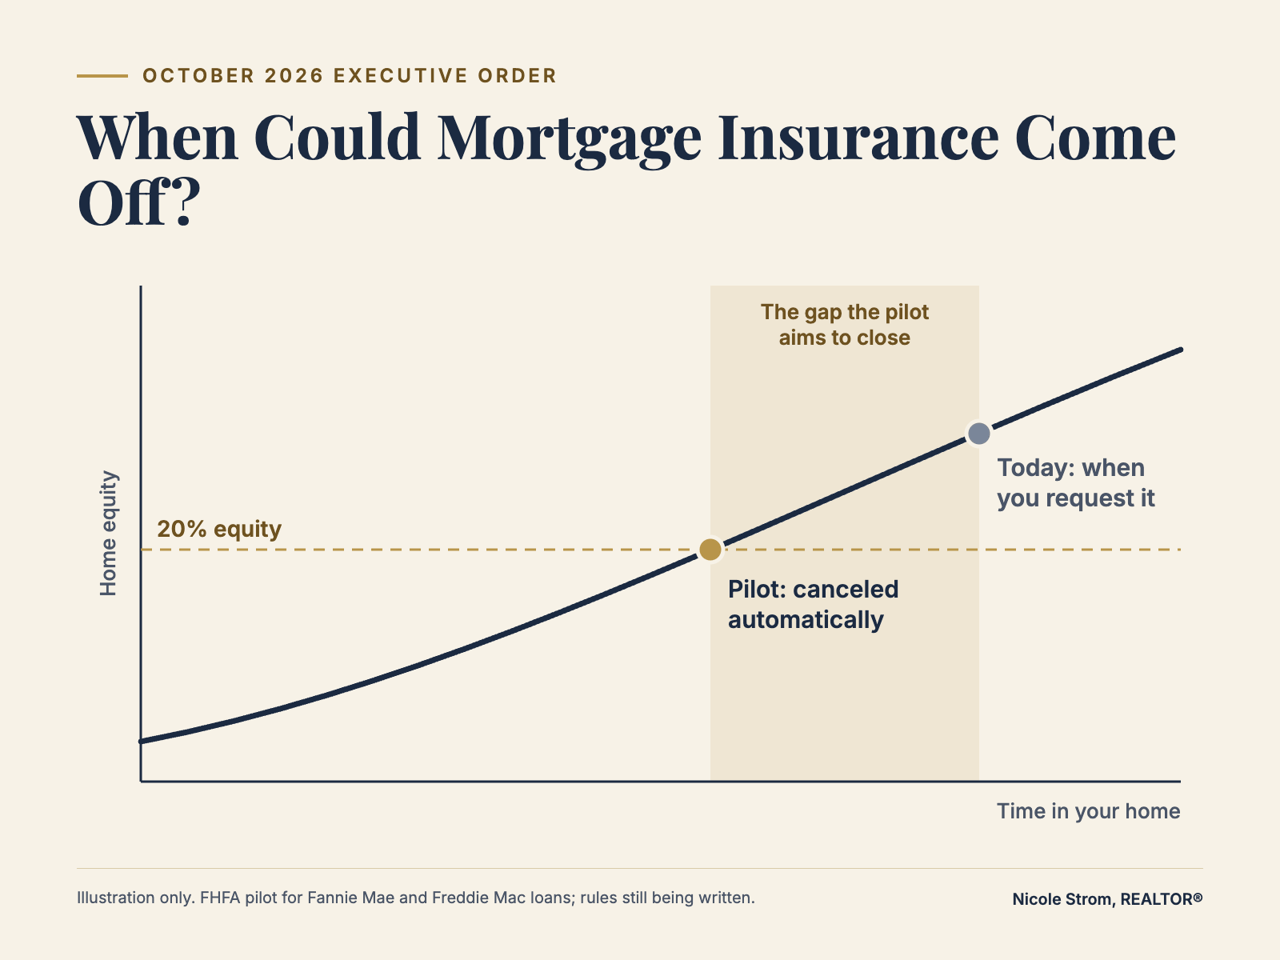
The pilot would use automated valuation models (AVMs) to periodically estimate home values. When a borrower has reached the required equity based on current market value, the program would proactively cancel their mortgage insurance, without the homeowner needing to gather extensive paperwork or pay for an appraisal.
What is mortgage insurance, and why do people pay it?
Mortgage insurance protects the lender, not the homeowner, if a borrower defaults. On conventional loans, it is typically required when a buyer puts down less than 20%. Once a homeowner has at least 20% equity, mortgage insurance is generally no longer required.
It is a tool that allows many buyers to purchase with a smaller down payment. The challenge has been getting it removed once equity builds.
How is mortgage insurance removed today?
Under current practice, mortgage insurance on a conventional loan drops off automatically based on the original loan schedule. If a homeowner wants it removed earlier because their home has gained value, they usually have to request it, meet the servicer’s requirements, and often pay for a new appraisal.
Many homeowners never make that request, simply because they do not know they can, or because the process feels like a hassle. That means some people keep paying for insurance they may no longer need.
What changes for refinancing?
The order also addresses refinance costs in two ways:
- Title insurance alternatives. FHFA is directed to expand its existing title insurance waiver pilot into a permanent program. For eligible refinances, an automated title review could be accepted in place of a traditional lender’s title insurance policy.
- Appraisal and documentation waivers. The order seeks to waive appraisals and certain documentation for qualifying refinances, with the stated requirement that cost savings be passed directly to borrowers.
Does this affect title insurance when I buy a home?
Based on what has been released, these title changes apply to the lender’s policy on eligible refinances. The owner’s title insurance policy that protects a buyer’s ownership on a purchase is a separate policy, and in my opinion it remains one of the most important protections in a real estate transaction.
Does this change my mortgage right now?
No. An executive order directs agencies to act, but the details still need to be built: eligibility rules, equity thresholds, how often values are reviewed, and which loans qualify. Nothing about an existing loan changes overnight.
Are there concerns about this approach?
Yes, and it is worth understanding both sides. Supporters see this as a way to reduce costs for homeowners who have already built equity. Mortgage insurers have raised concerns that automated value estimates are not always precise, which could shift risk. The title insurance industry has long opposed waiver programs, arguing that traditional title policies provide important protection. How FHFA writes the rules will shape how this plays out.
What does this mean for homeowners in the Pikes Peak region?
Many homeowners in El Paso County bought with less than 20% down, including a large number of military families using conventional financing. Depending on when you purchased and how values have moved in your neighborhood, your equity position today may look very different than it did at closing.
Frequently Asked Questions
Will my mortgage insurance be cancelled automatically now?
Not yet. The order directs FHFA to create a pilot program. Eligibility and timing will depend on the rules FHFA releases.
Does this apply to FHA loans?
FHA mortgage insurance is governed by its own set of HUD rules. The pilot described in the order is directed through FHFA for Fannie Mae and Freddie Mac loans.
What is an automated valuation model?
An AVM is a computer model that estimates a home’s value using data such as recent sales, property characteristics, and market trends. It does not involve an in-person visit.
Is the owner’s title insurance still recommended when buying?
Yes. The refinance changes address the lender’s policy. The owner’s policy protects your ownership interest in the property.
How do I know if I pay mortgage insurance?
Your monthly mortgage statement typically shows a breakdown of your payment, including any mortgage insurance.